

Gas Routes to Europe: Real Needs and Political Jockeying
The Energy Roadmap 2050 released by the Commission in December 2011 says it all: we will need more gas until 2030. Gas represents the default solution for a transition to an energy system with less GHG emissions. It also has great value as a back-up for intermittent renewable power generation. Therefore, stating that Europe still needs large quantities of gas means checking if supply volumes are available to satisfy growing demand.
Internationally there was an extraordinary abundance of gas in 2011, due to the expansion of US shale gas output. At the European level, the economic crisis and the particularly mild winter (until February 2012) further amplified this situation. European gas prices were far cheaper on spot markets and large volumes were still available in most countries.
Despite this context, European gas demand is set to increase and gas will represent one of the main energies in the fuel mix, in the years to come. In fact, situations differ from country to country, while European legislation aiming at lowering the carbon content of our economies and of our energy mixes will push member states (like Poland) to replace progressively more polluting fuels (coal and oil) with gas. Other political choices may influence gas demand, such as Germany’s exit from nuclear power. In fact, one of the fastest and cheapest solutions to replace base load nuclear generation is the construction of Combined Cycle Gas power plants.
As carbon capture storage is still waiting for favorable price signals, and as domestic gas production is diminishing rapidly in all Member States and EEA countries, attention is clearly focusing on the security of supply and on import infrastructures...

Available in:
Regions and themes
Share
This page contains only a summary of our work. If you would like to have access to all the information from our research on the subject, you can download the full version in PDF format.
Gas Routes to Europe: Real Needs and Political Jockeying
Center for Energy & Climate
Ifri's Energy and Climate Center carries out activities and research on the geopolitical and geoeconomic issues of energy transitions such as energy security, competitiveness, control of value chains, and acceptability. Specialized in the study of European energy/climate policies as well as energy markets in Europe and around the world, its work also focuses on the energy and climate strategies of major powers such as the United States, China or India. It offers recognized expertise, enriched by international collaborations and events, particularly in Paris and Brussels.
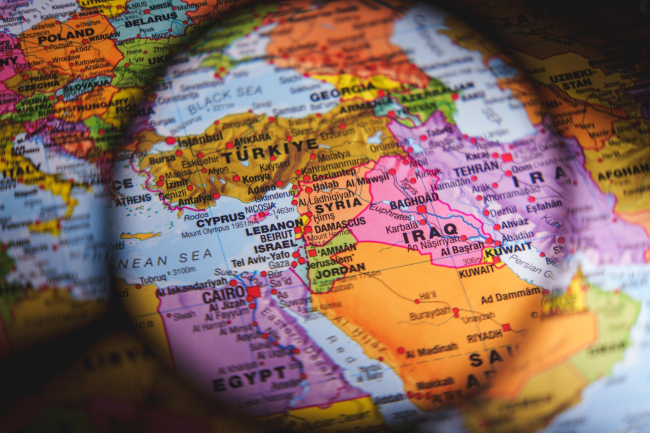
Strategic Redundancy beyond Hormuz: Alternative Oil and Gas Corridors and Türkiye’s Emerging Role
The central question raised by the present crisis in the Gulf and the disruption of navigation through the Strait of Hormuz is not simply how quickly and lastingly normal flows can be restored, but whether the regional energy architecture can continue to rely so heavily upon a single maritime corridor.
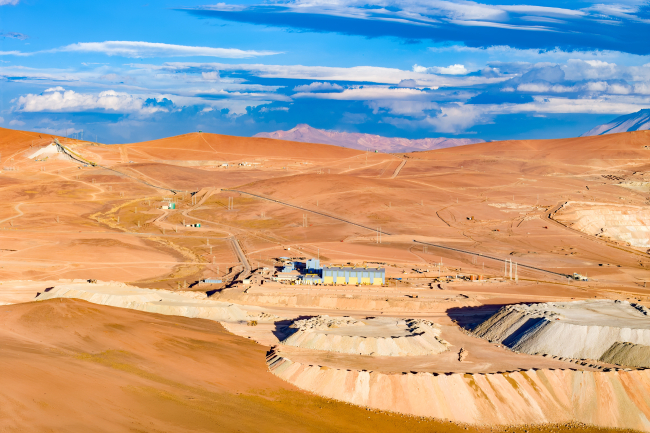
Mining Nationalism and Export Restrictions: The Challenges of Economic Development
Since the end of the 2000s and especially the 2010s, resource nationalism has been on the rise.
Solar Radiation Management: A Climate Tool with Geopolitical Implications
The Paris Agreement (2015) aims to keep global warming below 2 °C, preferably 1.5 °C, above pre-industrial levels. Mitigation (reducing greenhouse gas emissions) remains the core tool for reaching net carbon neutrality by mid-century. However, a temperature overshoot is anticipated. The United Nations Environment Programme (UNEP) forecasts that the 1.5 °C threshold will be exceeded in the coming years, with warming potentially peaking between 2.2 °C and 3.6 °C this century. Against this backdrop, three trends characterize the climate policy debate.
China’s Hydrogen Economy Five Years On
China’s hydrogen sector is not new. It is the world’s largest industrial hydrogen system, rooted in ammonia, methanol, refining, coal chemicals and by-product gas streams.