

India’s Broken Power Economics : Addressing DISCOM Challenges

India’s electricity demand is rising at an impressive annual rate of 9%. From 2014 to 2023, the country’s gross domestic product (GDP) surged from 1.95 trillion dollars ($) to $3.2 trillion (constant 2015 US$), and the nation is poised to maintain this upward trajectory, with projected growth rates exceeding 7% in 2024 and 2025. Correspondingly, peak power demand has soared from 136 gigawatts (GW) in 2014 to 243 GW in 2024, positioning India as the world’s third-largest energy consumer. In the past decade, the country has increased its power generation capacity by a remarkable 190 GW, pushing its total installed capacity beyond 400 GW.

India’s renewable energy sector is equally impressive, ranking fourth globally in total installed capacity. India reached its goal of sourcing 40% of its installed electric capacity from non-fossil fuels by November 2021. At COP26, the country took an ambitious leap, committing to 500 GW of non-fossil fuel-based energy by 2030. This bold commitment aligns with India’s pledge to cut projected carbon emissions by 1 billion tonnes and reduce the carbon intensity of its economy by 45% by the end of the decade.
Yet no sector embodies the nation’s “land of paradoxes,” quite like the power sector. On the one hand, it’s a success story: India has made remarkable strides in renewable energy generation and achieved near-universal household access to electricity. On the other hand, the sector remains plagued by inefficiencies in power generation, transmission, distribution, and financing. These challenges are compounded by the fiercely competitive landscape of “free electricity” promises at the state level.
Consumers still face frequent power cuts, especially during scorching summer months, and grapple with steep electricity prices, disproportionately affecting lower-income households. The root of these challenges lies in dysfunctional electricity politics, leaving India’s power economics in disarray. This troubling situation casts doubt on the future of sustained growth in renewable energy generation and underscores the urgent need for a critical reassessment of the path forward.

Available in:
Themes and regions
ISBN / ISSN
Share
This page contains only a summary of our work. If you would like to have access to all the information from our research on the subject, you can download the full version in PDF format.
India’s Broken Power Economics : Addressing DISCOM Challenges
Center for Energy & Climate
Ifri's Energy and Climate Center carries out activities and research on the geopolitical and geoeconomic issues of energy transitions such as energy security, competitiveness, control of value chains, and acceptability. Specialized in the study of European energy/climate policies as well as energy markets in Europe and around the world, its work also focuses on the energy and climate strategies of major powers such as the United States, China or India. It offers recognized expertise, enriched by international collaborations and events, particularly in Paris and Brussels.
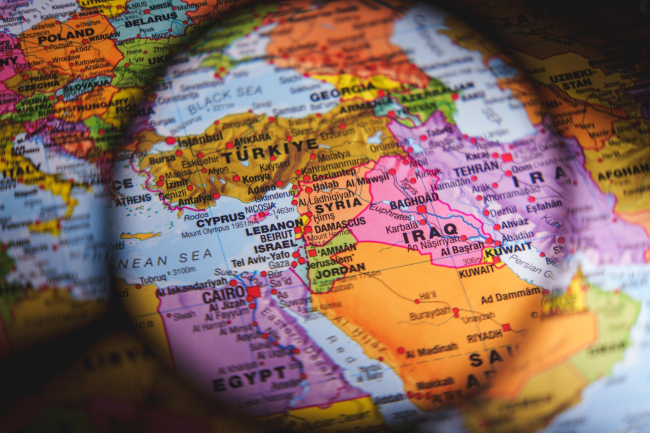
Strategic Redundancy beyond Hormuz: Alternative Oil and Gas Corridors and Türkiye’s Emerging Role
The central question raised by the present crisis in the Gulf and the disruption of navigation through the Strait of Hormuz is not simply how quickly and lastingly normal flows can be restored, but whether the regional energy architecture can continue to rely so heavily upon a single maritime corridor.
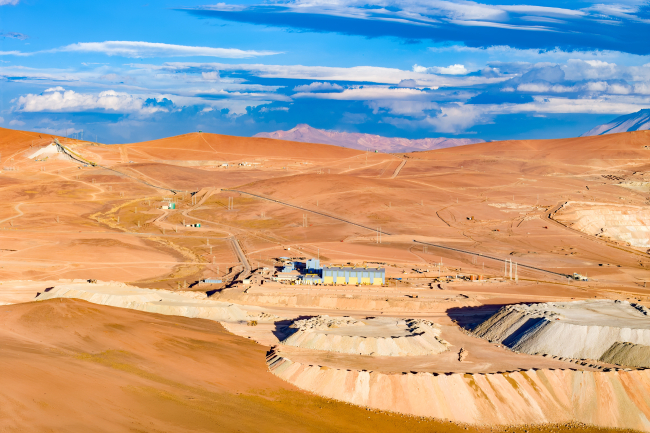
Mining Nationalism and Export Restrictions: The Challenges of Economic Development
Since the end of the 2000s and especially the 2010s, resource nationalism has been on the rise.
Solar Radiation Management: A Climate Tool with Geopolitical Implications
The Paris Agreement (2015) aims to keep global warming below 2 °C, preferably 1.5 °C, above pre-industrial levels. Mitigation (reducing greenhouse gas emissions) remains the core tool for reaching net carbon neutrality by mid-century. However, a temperature overshoot is anticipated. The United Nations Environment Programme (UNEP) forecasts that the 1.5 °C threshold will be exceeded in the coming years, with warming potentially peaking between 2.2 °C and 3.6 °C this century. Against this backdrop, three trends characterize the climate policy debate.
China’s Hydrogen Economy Five Years On
China’s hydrogen sector is not new. It is the world’s largest industrial hydrogen system, rooted in ammonia, methanol, refining, coal chemicals and by-product gas streams.